e-Invoicing France 2027: Timeline, Requirements, & Format


France's e-invoicing reform modifies how businesses established in France issue, receive and report their invoices. E-invoicing France went live on 1 September 2026. All VAT‑registered businesses must exchange structured, machine-readable invoices through a platform approved by the tax authority, the Direction Générale des Finances Publiques (DGFiP), and send certain transaction and payment data to the authorities.
Key Takeaways
- Receiving: Since 1st September 2026, all VAT-registered businesses established in France have had to be able to receive e-invoices.
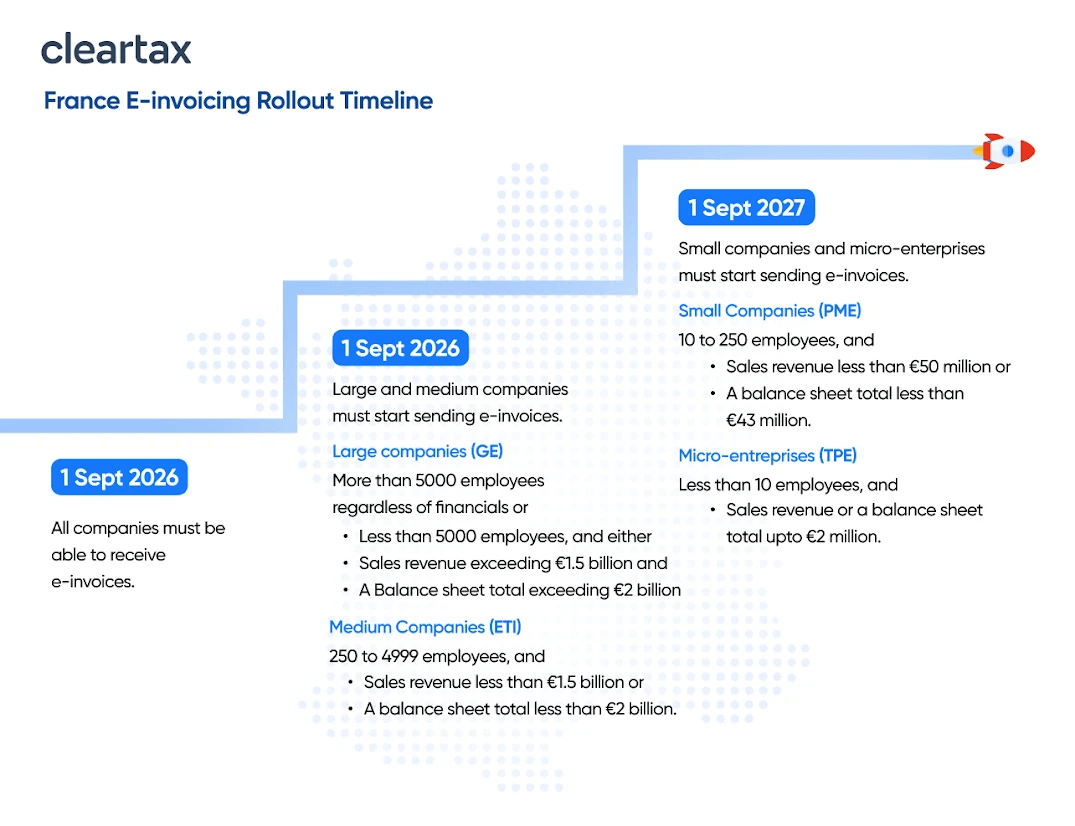
- Issuing and e-reporting: large companies and ETIs since 1 September 2026; SMEs and micro-businesses from 1 September 2027.
- Platform: invoices must travel through a DGFiP-approved platform. A PDF sent by email does not count as an e-invoice.
- Format: For B2B transactions, only structured electronic invoices are permitted. Traditional paper and standard PDF invoices are not accepted. The invoice should be in an accepted format, such as Factur-X, UBL, or CII. Transactions should be conducted through certified Approved Platforms (PAs).
- E-reporting: Mandatory for B2C, cross-border, and other non-B2B transactions.
What is e-Invoicing in France?
e-Invoicing in France means a process of creating, issuing, transmitting, and receiving invoices in structured electronic format. The invoice data must be readable by software, so that systems can validate it, route it to the right customer and pass the required information to the tax authority.
e-Invoices are exchanged through a plateforme agréée, or approved platform. Receiving and issuing are separate obligations. All of it must happen in accordance with the digital standards and platforms prescribed by law. This way, the information from the invoices can be automatically processed and reported to the French tax authorities.
A small business must not wait until September 2027 to arrange receipt of its suppliers’ electronic invoices.
Legal basis: Several laws have been enacted to ensure there is a legal framework for France’s compulsory use of electronic invoices. Article 26 III of loi n°2022-1157, as amended by article 91 of loi n°2023-1322; VAT-group reference: CGI article 256 C.
- Article 153 of the Finance Law in 2020.
- The implementation of the provisions was amended in Article 91 of the Finance Law of 2024, whereas Article 123 of the Loi de Finances pour 2026 (adopted 2 February 2026, promulgated 19 February 2026) has made the latest amendments.
France e-Invoicing Timeline and Compliance Deadlines
The original scheduled timeline of July 1, 2024, for the implementation of electronic invoicing was postponed. This gives everyone sufficient time to be prepared for this major change. New details on the implementation date and the prerequisites have been clearly set out in the latest Finance Law.
Who Needs to Comply with E-Invoicing in France?
In France, all companies with VAT obligations are subject to B2B e-invoicing. The obligation for e-Invoicing is applicable to businesses established in France and subject to VAT. Advance payments relating to those supplies are also in scope, as are certain sales of second-hand goods, works of art, collectors' items and antiques at public auction.
Businesses benefiting from franchise en base de TVA are also covered. Not charging VAT does not automatically remove a business from the reform: receiving, issuance and reporting obligations must be assessed separately.
| Category | Receive e-invoices | Issue in-scope e-invoices and perform applicable e-reporting |
| Large businesses - grandes entreprises | 1 September 2026 | 1 September 2026 |
| Intermediate-sized businesses - entreprises de taille intermédiaire | ||
| SMEs and micro-enterprises outside a VAT group | 1 September 2027 | |
| Members of a VAT group - assujetti unique |
e-Invoicing formats in France
A PDF sent by email is not an e-invoice under the reform. France provides for three structured formats, all aligned with the European standard EN 16931:
- UBL, an XML-based format. The core specification uses UBL 2.1
- UN/CEFACT CII (Cross Industry Invoice), another XML-based format.
- Factur-X, a hybrid format that combines a readable PDF/A-3 with embedded structured data.
The invoice must be in a structured format. As different businesses may use different formats, the approved platform usually converts between the those formats. This is how interoperability works and the counterparty does not need to use the same format as you.
Note: The Peppol BIS Billing 3.0 is a profile of UBL 2.1 and is not a separate authorised format. EDIFACT does not fall within the authorised formats under the French mandate and should be converted to one of the aforementioned three formats via the PA’s certification process.
Additionally, France gained status as a Peppol Authority on 8 July 2025.
e-Invoicing Requirements in France
All VAT registered businesses in France are needed to follow these requirements:
- Use an approved platform: All e-Invoices must be submitted through a government-approved platform. Each company must designate the platform it uses to issue and receive e-invoices and to report data. The tax authority publishes the list of registered platforms.
- Add four mandatory mentions in Invoices: DGFiP requires these additional mentions in an invoice; the SIREN number, the delivery address, mention of goods & services, details if opted to pay VAT on debits, where relevant.
- Handle invoice statuses: The lifecycle statuses of an invoice, such as submission, reception, rejection, or refusal. For transactions where VAT becomes due on payment, payment status must also be reported.
- E-report: Transaction data and payment information to be supplied to the tax authority.
- Maintain the records: Invoices must be kept in electronic form for six years from the date of issue.
How France E-Invoicing Works: Step-by-Step Process
1. Create the invoice with the ERP or an invoicing tool with all mandatory data, in a permitted structured format.
2. Issue the invoice to your approved platform. Your approved platform checks the invoice and its data.
3. Submit it to the customer's platform. Your platform will find the buyer in the national central directory (the Annuaire), which holds company identifiers and routing information.
4. Transmit the invoice through an identified route to the buyer's platform.
5. Send invoice data to authorities through the platforms.
6. Exchange statuses, such as received, rejected, refused, or paid along the same route.
7. E-report for B2C and cross-border transactions to the authority.
8. Archive, the e-Invoice in its electronic form for the required period.
French E-Invoicing Model and Framework
France uses a decentralised model for invoice-exchange which is often called a "Y-model". It's also called a five-corner model like Spain's Crea y Crece. On the other hand UK and Germany follow decentralized 4-corners model. Following are the counterparts and their obligations in France:
- Businesses: Issue, receive and pay invoices, and designate their platform.
- Approved platforms (Plateformes Agréées, formerly called PDPs): Intermediaries handling invoice exchange and required data transmission.
- Public invoicing portal - PPF: It manages the central directory and concentrates required regulatory data.
- Chorus Pro: It's a platform for invoices to public-sector buyers.
- DGFiP: Government authority that receives and uses the tax data.
Who is exempted from e-invoicing?
Few businesses are fully exempt, but some transactions fall outside the e-invoicing obligation:
- Sales to consumers (B2C) are not e-invoiced, but they are subject to e-reporting.
- Cross-border transactions of sales and purchases between foreign businesses are excluded. But they generally covered by e-reporting instead of domestic e-invoicing.
- VAT-exempt supplies. Operations that are exempt from VAT are generally outside e-invoicing.
- Businesses not established in France, for the domestic e-invoicing obligation.
- Certain overseas territories, such as French Guiana and Mayotte, where VAT does not apply.
- There is no exemption from the duty to receive for small businesses. A micro-business that does not need to issue until 2027 still needs a platform to receive e-invoices from its suppliers.
A taxable business carrying out exempt sales can still have to receive electronic invoices from suppliers.
France E-Invoicing Compliance Guidelines for Businesses
A practical checklist for businesses to prepare for France mandate compliance invoives fundamental requirements as below:
Firstly, classify your domestic B2B, B2C, B2G, international and exempt transactions and confirm their implementation phase as per the mandate dates. Next, Confirm it supports the permitted formats, connects to your ERP and handles statuses and e-reporting. Also, check your data, identifiers (SIREN and SIRET), addresses and VAT details as they need to be accurate.
Next, choose and connect a platform. You can verify the status of your approved platform in the official DGFiP directory. From here, you must check receiving-platform designation and directory routing.
After platform selection and appointment, clean customer identifiers, addresses and tax-treatment data. You must assign the responsibilities across your finance, tax, IT and operations teams. Also, test invoices, credit notes, refusals, rejections and payment reporting. Preserve records and reconcile reporting with accounting processes.
France E-Invoicing Penalties for Non-Compliance
The relevant penalties were updated by article 123 of the 2026 Finance Act. Application follows the relevant reform phase.
| Failures | Penalty |
| Failure to issue a electronic invoice | EUR 50 per invoice. (Capped at EUR 15,000 per calendar year) |
| Failure to meet transaction e-reporting obligations | EUR 500 per transmission. (Capped at EUR 15,000 per calendar year) |
| Failure to meet payment-reporting obligations | EUR 500 per transmission. (Capped at EUR 15,000 per calendar year) |
| Failure to use an approved platform for receipt | EUR 500 after an unsuccessful first three-month formal-notice period; EUR 1,000 after the next, with further EUR 1,000 fines after subsequent unsuccessful notice periods |
Additional Notes:
- Penalties will be levied separately for violations of electronic invoices and reports.
- The penalty for failure to provide correct invoice data shall not exceed 25% of the total amount of the invoice.
- Fraudulent invoicing carries a heavy penalty due to its importance in tax evasion.
- Penalties are cumulative and may be levied alongside other fines.
- The annual limit on penalties imposed on PAs is higher than that for others, given their importance.
- On 7 May 2026 (annual E-Invoicing Day), the Director General of DGFiP, Amélie Verdier, stated that no penalties will be imposed from 1 September 2026, as there will first be contact with businesses before any enforcement can occur.
What is e-Reporting in France?
e-Reporting in France refers to the electronic transmission of specific transactional and payment data to the French tax authorities for certain operations that are not covered by the mandatory B2B e-invoicing regime.
Who Must Perform e-Reporting?
- French Businesses: Every business incorporated in France should electronically report those transactions that fall outside the scope of the e-invoicing obligation.
- Foreign Businesses: Any business registered for VAT in France but that does not have a permanent establishment in France should also report electronically.
Who must comply with e-Reporting Obligations?
As per the French tax administration, the transactions that should be reported electronically are:
- Business to Consumer (B2C): The sales of goods/services by businesses in France to consumers (not applicable for B2B electronic invoicing).
- Exports: The supplies of goods/services from France to countries which are not part of the European Union.
- Imports: The purchases of goods/services by businesses in France from countries which are not part of the European Union.
- Intra-community EU Exports: The exportation of goods and services from France to other EU member countries.
- Intra-community EU Imports: The importation of goods and services into France from other EU member countries.
Why is e-invoicing being introduced in France?
The French Government is committed to the implementation of e-invoicing for businesses. This reform aims to:
- Enhance their competitiveness by reducing administrative burden and increasing productivity through dematerialization.
- Simplify reporting obligations by automating VAT declarations.
- To avoid fraud cases and favour the legitimate businesses
- Improve real-time visibility into business operations.
How ClearTax Can Help with e-Invoicing Implementation in France
ClearTax is now an Approved Platform (PA) for France e-invoicing and e-reporting, recognized under the French tax administration’s accreditation framework providing legal authority to help businesses issue, receive, validate, route, and report compliant electronic invoices under France’s 2026 mandate.
- Connect effortlessly with any ERP or POS system via APIs.
- Compliant e-invoice exchange with the French Public Portal (PPF).
- Manage e-invoicing and compliance from a single secure dashboard.
- Automatic updates to stay compliant with French regulations.
- 99.99% uptime for uninterrupted invoicing.
- Advanced validation for faster, error-free processing.
- Instant alerts for invoice status changes.
- Automated updates to improve vendor and customer interactions.
Frequently Asked Questions
About Author
I’m a Senior Content Writer at ClearTax, specializing in e-invoicing, VAT, and Tax compliance. Over the years, I’ve researched and written everything from blog posts to whitepapers and product guides, helping ClearTax expand in Malaysia, KSA, UAE, Singapore, Belgium, France and beyond. My goal is to write the most comprehensive, understandable, readable, and accurate content on any topic that has ever existed on the internet. Outside of writing, I love reading self-help books, creating videos, and playing video games.

Rajan Rauniyar
Senior Content Writer- International


