|
e-Invoicing in Philippines 2026: Timeline, Requirements, Process and Penalties


e-Invoicing in Philippines is the legal move to replace manual invoices with system-generated electronic invoices. It matters because from 31st December 2026, large taxpayers, e‑commerce firms, and CAS users must issue e-invoices. The BIR EIS has set strict rules, and the penalties are heavy.
Key Takeaways
- The e-invoicing deadline for the specified taxpayers is from 31st December 2026, as per the BIR RR No. 11-2025 and 26-2025.
- Specified taxpayers are large taxpayers under BIR and EOPT Act, e-commerce businesses, and CAS/CBA users.
- E‑Invoice Philippines must be generated by the system in structured JSON format and sent to the BIR.
- You get additional tax incentives like a setup cost deduction at 100% if you are a Micro and Small taxpayer and 50% as a Medium and Large taxpayer under the CREATE MORE Act.
- If you fail to meet E-invoicing laws, you will attract a penalty of ₱1,000 to ₱50,000 per offence.
What is e-Invoicing in Philippines?
e-Invoicing in Philippines is the process of raising, sending, and storing invoices in a structured electronic format using the BIR-registered software or systems. It is not the same as a scanned paper copy or a PDF saved from a Word file.
Philippines e-Invoice is a compliant e-invoice generated by the system with structured, machine-readable data. A PDF sent to the buyer can qualify if it is generated by a compliant system. Key documents covered under the EIS include sales invoices, official receipts, service billings, debit notes, and credit notes.
Specified businesses must issue e-invoices to buyers using their registered invoicing systems. Sending sales data to the BIR through EIS is a separate requirement and will follow further BIR guidelines.
Below laws govern Philippines e-invoicing mandates:
- e-Invoicing provisions are in the Sections 237 and 237-A of the National Internal Revenue Code (NIRC), as amended by the CREATE MORE Act.
- You can know the implementation rules primarily from the Revenue Regulations No. 11-2025 (dated 27th February 2025).
- 31st December 2026 is new e-Invoicing deadline as per the Revenue Regulations No. 26-2025 (dated 5th September 2025).
- The new Revenue Regulations No. 98-2026 (dated 22nd September 2026) explains how businesses must issue electronic invoices and makes clear that electronic sales reporting is separate.
e-Invoicing Philippines Timeline (Mandatory Date 2026)
The Philippines e-Invoicing is implemented in phases. Here is the timeline from pilot to the current mandatory deadline.
Timeline / Date | Milestone |
31 December 2026 | The current deadline for Group 1 taxpayers is to issue structured e-invoices by this date |
TBD | Group 2 taxpayers (exporters, POS users, RBEs), where the deadline is yet to be announced in a separate Revenue Regulation once the BIR system is ready, except those already in Group 1, including CAS/CBA or other invoicing software users. |
| 22 September 2026 | BIR issues new guidance on e-invoice issuance, the PTI, and separate sales reporting. |
5 September 2025 | BIR issues RR No. 26-2025, extending the compliance deadline |
14 March 2025 | RR No. 11-2025 takes effect (15 days after publication) |
27 February 2025 | BIR issues RR No. 11-2025- the primary e-invoicing regulation under CREATE MORE |
2024 | The CREATE MORE Act (RA 12066) and the EOPT Act (RA 11976) were enacted; the e-invoicing framework was significantly expanded |
November 2023 | BIR acknowledges technical challenges with the EIS; pilot effectively paused |
July 2022 | BIR launches pilot e-invoicing program for the 100 largest taxpayers (B2G transactions under RR 8-2022) |
Who Needs to Comply with e-Invoicing in the Philippines?
RR No. 11-2025 divides covered taxpayers into two groups with different obligations and timelines.
Group 1 - Mandatory Deadline: 31st December 2026
The following taxpayers must issue structured e-invoices by 31st December 2026:
- E-commerce and internet businesses- Businesses selling digital goods, digital content, online services, digital financial services, online entertainment, or conducting social/platform commerce transactions (classified as Small, Medium, or Large Taxpayers)
- Large Taxpayers under the BIR's Large Taxpayers Service (LTS)
- Large Taxpayers classified under the Ease of Paying Taxes (EOPT) Act (RA 11976) and RR No. 8-2024, generally businesses with annual gross sales exceeding PHP 1 billion
- Businesses using Computerised Accounting Systems (CAS), Computerised Books of Accounts (CBA) with electronic invoicing, or other invoicing software capable of producing structured data
Important: If a business has a head office and branch offices, all locations must comply, not just the head office.
Group 2 - No Firm Deadline Yet (Pending BIR System Readiness)
The following taxpayers will be required to comply only after the BIR establishes a system capable of storing and processing the required data. A separate Revenue Regulation will set their deadline.
- Exporters of goods and services (under Sections 106 and 108 of the Tax Code), except such exporter or PEZA/BOI enterprise already running SAP or Oracle is covered in the first wave, due 31 Dec 2026.
- Registered Business Enterprises (RBEs) availing of tax incentives under Section 304(D)
- Point-of-Sale (POS) system users
- Other taxpayers as designated by the BIR Commissioner
e-Invoicing Format in Philippines
JSON (JavaScript Object Notation): The BIR-prescribed format for electronically transmitting sales data. It allows invoice information to be structured and processed by systems.
Other structured formats: Businesses can use other structured formats in their accounting or invoicing systems, provided the data can be converted to the BIR-prescribed JSON format when required.
PDF: An e-invoice can be delivered as a PDF attachment, provided it is generated from structured invoice data by a compliant system.
e-Invoicing Requirements in Philippines
To issue a compliant e-invoice, businesses must meet the following requirements under RR No. 11-2025.
1. Use EIS-Compliant Software
It's recommended to choose an EIS-compliant e-invoicing software to generate structured invoices. Your invoicing system, or any standalone billing software, must generate structured invoice data and issue the invoice electronically to the buyer. It should also be ready for BIR sales reporting when separately required.
Always select and evaluate your ASP against BIR's published technical specifications.
2. Obtain a Permit to Issue (PTI) Electronic Invoice
Covered businesses must obtain a Permit to Issue (PTI) Electronic Invoice from the BIR before issuing e-invoices. Apply through the RDO or Large Taxpayer Office where you are registered. The BIR reviews complete applications within 20 working days. EIS Certification is required within six months after the PTI is issued. A Permit to Transmit (PTT) will be required only when the BIR directs businesses to start electronic sales reporting.
3. Issue Invoices in Structured Format
The invoice must come from a compliant system and contain structured data. The BIR currently uses JSON for sales-data reporting, but other structured formats may be used internally. A PDF emailed to the buyer can qualify if it comes from a compliant system. Manually made Word files, PDFs, and scans do not qualify.
4. Include All Mandatory Fields
E-invoices must include the mandatory invoice information under the applicable BIR rules. The main fields to check are listed below.
5. Prepare for BIR Sales Reporting
The 31st December 2026 deadline is for issuing e-invoices, not for sending every invoice to the BIR. Electronic sales reporting will follow separate BIR guidelines. The Permit to Transmit and any reporting timeline will apply when the BIR directs the taxpayer to start reporting.
6. Maintain a Digital Archive
Businesses must keep a retrievable electronic archive of all issued invoices and transmission logs, accessible to the BIR during audits.
- Unique document ID (linked to the transaction)
- Issue date and precise timestamp
- Seller's legal name, address, and BIR TIN
- Buyer's legal name, address, and BIR TIN
- Line items for goods/services description, quantity, and unit
- Taxable value, charges, discounts, and adjustments
- VAT rate (12% VATable, 0% Zero-Rated, or VAT-Exempt)
- Tax label: 'VATables Sale', 'Zero-Rated Sale', or 'VAT-Exempt Sale'
- Grand total (including taxes)
How Philippines e-Invoicing Works: Step-by-Step Process
Step 1: Register with the BIR EIS Portal
The business registers on the BIR EIS portal and applies for EIS Certification. Only taxpayers mandated or notified by the BIR can register. Once approved, the BIR grants a Permit to Transmit (PTT).
Step 2: Integrate Your Invoicing System
Link your ERP, accounting, or billing software to the BIR EIS using a system-to-system API. You must generate structured invoice data in JSON format that is as per the BIR's invoice schema format.
Step 3: Generate the e-Invoice
When you have a transaction, the system automatically generates a structured invoice with all mandatory fields. It replaces manual paper invoices or unstructured PDF.
Step 4: Transmit Data to the BIR EIS
The invoice data is transmitted via API to the BIR EIS. The BIR platform validates the data against the prescribed schema.
Step 5: Issue the Invoice to the Buyer
Once the e-invoice is generated and transmitted, it is issued to the buyer. Both the business and buyer can access the transaction digitally for reconciliation and audit purposes.
Step 6: Archive the Records
All e-invoices and transmission logs are stored in a digital archive. Electronic records replace paper copies, subject to BIR system readiness.
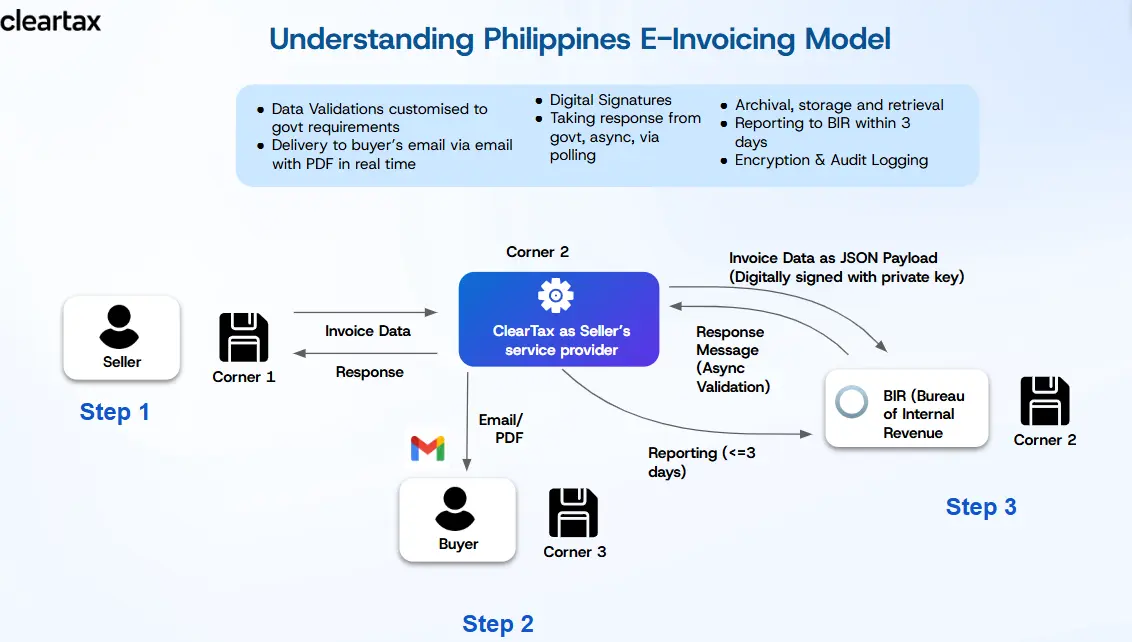
Philippines e-Invoicing Model
The Philippines e-invoicing framework can be understood from the chart below:
Who is Exempted from e-Invoicing?
Under RR No. 11-2025, the following taxpayers are not currently required to issue structured e-invoices:
Taxpayer Type | Status | What They Can Do Instead |
Micro Taxpayers (below the EOPT Micro threshold annual gross sales below PHP 3 million) | Exempt- mandatory requirement does not apply | Issue registered manual invoices; may voluntarily use CAS, CRM, or POS systems |
Exporters of goods and services | No firm deadline- Group 2 (unless already in Group 1) | Comply once BIR establishes a capable system; deadline TBD via separate RR |
Registered Business Enterprises (with tax incentives) | No firm deadline- Group 2 (unless already in Group 1) | Comply once BIR establishes a capable system; deadline TBD via separate RR |
POS system users | No firm deadline- Group 2 | Comply once BIR establishes a capable system; deadline TBD via separate RR |
Note: Micro Taxpayers who voluntarily adopt e-invoicing and electronic sales reporting can still claim the additional deduction on setup costs under the CREATE MORE Act.
e-Invoicing Compliance Guidelines
1. Confirm Applicability and Deadline
Verify if your business is classified as a large taxpayer, e-commerce business, CAS/CBA user, or exporter. Check whether you fall under Group 1 (31st December 2026) or Group 2 (TBD).
2. Audit Your Invoicing Infrastructure
Get a confirmation from your current ERP, billing, or accounting software provider if it can produce structured invoice data and issue e-invoices to buyers. Having an existing CAS permit does not replace the new PTI Electronic Invoice.
3. Obtain the PTI and EIS Certification
Apply for the PTI Electronic Invoice through your RDO or Large Taxpayer Office before issuing e-invoices. Obtain EIS Certification within six months of the PTI. The PTT is for BIR sales reporting when separately required.
4. Integrate and Test Your System
Test invoice generation, structured data, and electronic delivery to buyers. Prepare BIR EIS API transmission separately for when sales reporting applies. Resolve exceptions before the deadline.
5. Train Your Finance and IT Teams
Brief your finance, accounting, and IT staff for the new workflow.
6. Ensure All Offices Are Covered
If your business has branches, all offices must comply including the head office. Document branch readiness as part of your transition plan.
7. Maintain Clean Data Hygiene
Clean up your chart of accounts, buyer TIN records, invoice data fields, and transaction tagging before the deadline. Inaccurate master data will cause transmission failures.
Philippines e-Invoicing Penalties for Non-Compliance
Not complying with the Philippines e-invoicing mandate leads to serious financial and operational hurdles. Applicable penalties under the Tax Code are below-
Taxpayer Type | Status | What They Can Do Instead |
Micro Taxpayers (below the EOPT Micro threshold annual gross sales below PHP 3 million) | Exempt- mandatory requirement does not apply | Issue registered manual invoices; may voluntarily use CAS, CRM, or POS systems |
Exporters of goods and services | No firm deadline- Group 2 | Comply once BIR establishes a capable system; deadline TBD via separate RR |
Registered Business Enterprises (with tax incentives) | No firm deadline- Group 2 | Comply once BIR establishes a capable system; deadline TBD via separate RR |
POS system users | No firm deadline- Group 2 | Comply once BIR establishes a capable system; deadline TBD via separate RR |
Benefits of e-Invoicing for Philippine Businesses
Switching to e-invoicing offers concrete advantages, both financial and operational.
- Additional Tax Deduction (CREATE MORE Act)
Businesses that adopt e-invoicing and electronic sales reporting (mandated or voluntarily) can claim an extra deduction from taxable income: 100% of setup costs for micro and small taxpayers, and 50% for medium and large taxpayers. It is on top of the standard deduction under Section 34(A)(1) of the Tax Code. The deduction can be claimed once within the taxable year the system is completed, or the final payment is made.
- Reduced Manual Effort
Finance teams will start spending lesser time and lower manual efforts on billing, reconciliations and tax reporting since invoice generation and transmission all get automated.
- Fewer Errors
There’ll be drastic fall in human errors because of structured and consistent invoice data formats, in the areas of VAT calculations, tax reporting, and record-keeping.
- Real-Time Audit Readiness
Digital archives and transmission logs mean businesses are audit-ready at any time, reducing the risk of disputes and re-work.
- Cost Savings
Eliminating printing, physical storage, and manual data entry reduces operational costs over time.
- Faster Reconciliation
Automated invoice matching speeds up payment cycles and improves cash flow management.
- Fraud Prevention
Traceable digital records make invoice manipulation and tax evasion harder to execute.
- Exemption from Summary List of Sales (SLS)
Taxpayers using the EIS are exempt from filing the traditional Summary List of Sales, being one less periodic compliance obligation.
How ClearTax Helps to Simplify Philippines e-Invoicing Compliance?
The mandate requires covered taxpayers to issue compliant e-invoices by 31st December 2026. Sending sales data to the BIR is a separate requirement. ClearTax offers a complete e-Invoicing Software Solution that removes the need for in‑house development by finance and IT teams.
With ClearTax, businesses can:
- Connect with your existing systems: Integrate with 60+ ERPs and billing solutions, including SAP, Oracle and Microsoft Dynamics.
- Prepare compliant invoice data: Convert invoice data into the BIR’s JSON format, apply the JWS signature and validate files before submission when sales reporting applies.
- Simplify BIR reporting: Submit sales data to the EIS through APIs, with built-in confirmation, error handling and resubmission.
- Keep records secure: Store invoices and related documents securely for 10 years, with reconciliation and audit support.
- Get compliance support: Get support with CAS registration, PTI Electronic Invoice, EIS Certification and Permit to Transmit requirements when applicable.
- Stay up to date with BIR changes: ClearTax updates its platform to reflect changes to EIS rules and timelines, helping businesses keep their processes aligned.
- Manage e-invoicing across markets: Use one platform to manage e-invoicing across 50+ countries, with ClearTax’s global e-invoicing experience since 2017.
Frequently Asked Questions
About the Author

Annapoorna
I preach the words, “Learning never exhausts the mind.” An aspiring CA and a passionate content writer having 8+ years of hands-on experience in deciphering jargon in Indian GST, Income Tax, off late also into the much larger global compliance ecosystem spanning SEA, GCC, USA and EU. I love curating content in various forms to the interest of tax professionals, and enterprises, both big and small. While not writing, you can catch me singing Shāstriya Sangeetha and tuning my violin ;). Read more


Cleartax is a product by Defmacro Software Pvt. Ltd.
Your data security and privacy matter most to us.